The best cashback card is the one whose qualifying purchases match your spending after its fees and restrictions. A large headline percentage is not enough: it may depend on a particular merchant, payment channel, account plan, spending tier or credit limit.
Source review, 7 November 2026: we have withdrawn universal annual-return rankings where the source conditions cannot be modelled reliably. Some issuer pages and linked documents disagree. The linked profiles identify those conflicts; a pending figure is not zero, and a retained source-record date is not a new whole-card verification.
Start with the purchases you already make
| Your main question | Profiles to examine | What can change the result |
|---|---|---|
| Restaurant bills and food delivery | Mashreq Cashback, ADCB 365, FAB Cashback | Eligible merchant categories, spending gates, statement caps and assigned-credit-limit restrictions |
| Everyday purchases across different merchants | Citi Cash Back, Liv Cashback, Wio Credit | Transaction currency, spending tier, account plan and reduced-category treatment |
| A particular retailer or delivery platform | noon One, ADCB talabat | Named-platform eligibility and whether the reward is restricted credit rather than cash |
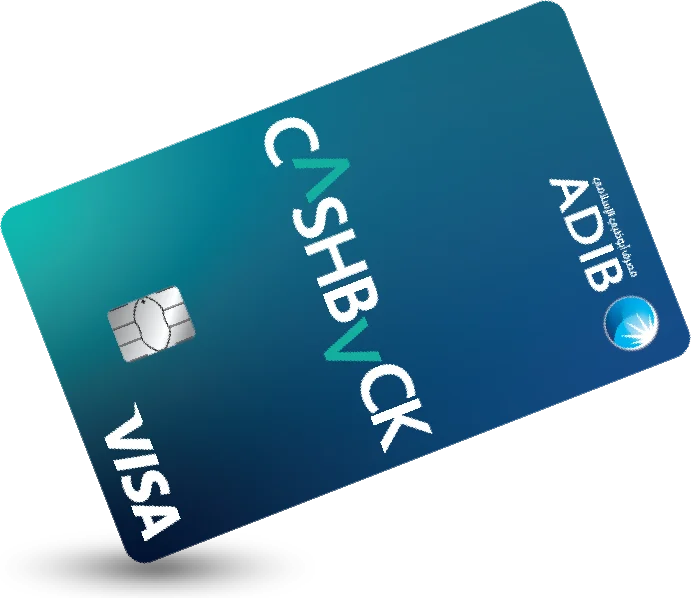
| A Sharia-compliant product | ADIB Cashback Visa, Emirates Islamic Switch | Product-specific qualification, reward mode, caps and the applicable charge schedule |
These are comparison routes, not an ordered list of winners or a recommendation that you qualify.
Compare the recorded facts
The tables read the same card records as the individual profiles. Known fees retain their VAT treatment; unresolved terms remain pending. Rewards for specified qualifying purchases must not be treated as a flat return on all spending.
Mashreq Cashback and ADCB 365
| Measure | Mashreq Cashback Credit Card |  Card image: adcb.com |
|---|---|---|
| Fees | ||
| Annual fee (year 2+) Annual fee year 2+ | Free ↗ | AED 383.25 (incl. VAT) |
| Eligibility | ||
| Minimum salary Min salary | AED 5,000/mo | Pending |
| Earn | ||
| Top earn rate Top earn rate | — | Dining 6% |
| Benefits | ||
| Welcome bonus Welcome bonus | AED 500 welcome bonus for new credit-card customers (AED 100 for existing customers) on AED 5,000 of spend within the first 2 months. | AED 365 welcome bonus — AED 5,000 spend within 45 days of issuance. |
| Lounge access Lounge access | Pending | Pending |
FAB Cashback and Citi Cash Back
| Measure | FAB Cashback Card  Card image: bankfab.com |  Card image: citibank.ae |
|---|---|---|
| Fees | ||
| Annual fee (year 2+) Annual fee year 2+ | AED 315 (incl. VAT) | AED 315 (incl. VAT) |
| Eligibility | ||
| Minimum salary Min salary | AED 5,000/mo ↗ | AED 8,000/mo |
| Earn | ||
| Top earn rate Top earn rate | — | — |
| Benefits | ||
| Welcome bonus Welcome bonus | Welcome offer pending source review. | Citi’s product page advertises an AED 300 joining-bonus statement credit for eligible direct applicants on AED 6,000 of qualifying spend within 60 days. Check the terms shown for your application route. |
| Lounge access Lounge access | Pending | Mastercard Travel Pass — 8 visits/yr |
Build a spending check before a return estimate
Use a recent statement and separate restaurant bills, supermarket payments, fuel, subscriptions, bills and overseas purchases. Then check the issuer’s definition of each category. A supermarket checkout is not necessarily the same category as a grocery order placed through a delivery platform.
For each card, establish:
- Which transactions qualify, including the payment channel and merchant classification.
- Whether the spending gate uses this statement, the previous month or another period.
- Which purchases count towards that gate and which earn a lower rate or nothing.
- Whether the cap applies per category, across rewards, to a credit limit or across account products.
- How cashback is redeemed, and whether redemption or expiry restrictions apply.
Only then calculate the reward on eligible spending, apply the relevant caps and deduct the costs that actually apply to you. Do not count the same purchase twice because it is both online and overseas.
Treat account-linked and platform rewards separately
Liv’s spending tiers and credit-limit cap, and Wio’s account-plan and shared-cap conditions, need more than a generic salary or spending total. Confirm the actual plan and its costs before comparing their advertised returns.
Likewise, noon credits and talabat credit have a different redemption universe from cash. Compare them only against purchases you would make on those platforms anyway, and read the exact welcome-offer conditions rather than assigning the headline award a cash value.
Before applying
Check the current application route, standard fee, any first-year or renewal waiver, and the issuer’s own eligibility decision. An advertised minimum salary is not approval. For overseas use, distinguish an issuer charge from additional scheme or merchant conversion charges.
Use the Card Finder to explore the recorded profiles, compare a shortlist and open each card’s source notes. For restaurant-specific choices, continue to the dining guide.