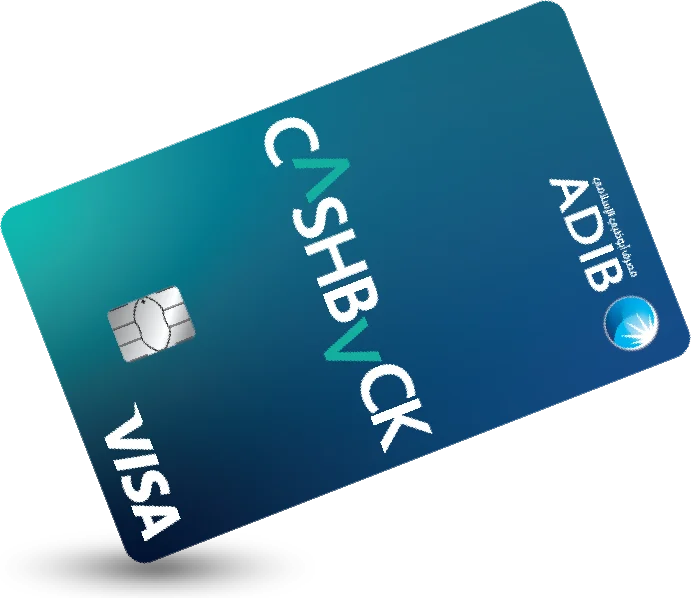
The ADIB Cashback Visa is a Sharia-compliant covered card that pays 4% on five everyday categories — and nothing outside them.
- Annual fee
- AED 103.95 incl. VAT
- Min salary
- AED 5,000/mo
Pros
- 4% cashback on grocery, fuel, education, dining and utilities — a high rate across core household categories
- Low AED 5,000 minimum salary, published in the Key Facts Statement
- Sharia-compliant covered card with roadside assistance and four free supplementary cards
- No minimum-spend gate to start earning, unlike some rivals
- Grace period up to 55 days
Cons
- Cashback is earned on five listed categories only — general and international spend earns nothing
- Caps blunt the rate — AED 300 on grocery/fuel/education, AED 200 dining, AED 100 utilities, AED 1,000 total a month
- Annual fee is quoted ex-VAT (AED 99 → AED 103.95 with VAT)
- 3.75% monthly profit rate (45.63% APR) — only worth holding if you settle in full
- The foreign-currency charge needs VAT and scheme treatment reconciled before an all-in comparison
Earn rates
Cashback is 4% on the listed categories only, each with a monthly cap. The table shows the categories our comparison engine can map; the full list is in the note:
- Everything else
- Pending
Stored category set omits education and utility rewards. Source category-specific caps and qualifying-spend conditions must be reconciled before arbitrary-spend calculations.
Fee summary
The current product copy and the earlier structure description are not reconciled, so we use the general Sharia-compliant covered-card description. The issuer’s foreign-currency service charge also needs its applicable VAT and separate scheme treatment made explicit; we do not claim a precise all-in rate or a fee advantage.
What you get — per-benefit value
4% cashback on the five categories
Worked at a spread household: AED 2,500 supermarkets (4% = AED 100), AED 750 fuel (AED 30) and AED 1,000 dining (AED 40) a month — all inside the AED 300/300/200 caps — is AED 170/month. Value to me: ~AED 2,040/year on that profile. The absolute ceiling is the AED 1,000 total monthly cap — AED 12,000/year — but reaching it takes roughly AED 25,000 of monthly spend spread across all five capped categories; treat it as theoretical.
Roadside assistance and supplementary cards
Once-a-year roadside assistance and four free supplementary cards. Value to me: AED 0 most years — the assistance pays only in the year you call it out, and free supplementary cards are a saving only against a card that would otherwise charge for them.
Total package: ~AED 2,040/year of cashback on the spread-household profile against the AED 103.95 fee (AED 99 + VAT) — the fee is recovered inside the first month of capped-category spend. The card adds nothing on general or international spend, so that figure is also the whole story.
Key conditions to know
- Caps
- AED 300 each on grocery, fuel and education; AED 200 dining; AED 100 utilities; AED 1,000 total per month. The 4% rate suits spread spend, not one large category.
- No minimum-spend gate
- Unlike some rivals, there is no minimum monthly spend to begin earning cashback.
- Excluded spend
- General retail, dining outside coded restaurants, and international spend earn nothing on this card.
- Supplementary cards
- Four free supplementary cards; the fifth and beyond carry the AED 99 fee. Roadside assistance once a year.
- Eligibility
- Minimum monthly income AED 5,000 (per the Key Facts Statement); UAE residency required.
Watch out for
- Five categories only. Like DIB’s card, this earns nothing on general or international spend — pair it with a flat-rate card.
- Caps come quickly. The AED 1,000 total cap and the per-category limits mean the 4% headline suits moderate, spread spend.
- Ex-VAT pricing. Fees are quoted before VAT — budget the AED 99 fee as AED 103.95.
- The current product copy and the earlier structure description are not reconciled, so we use the general Sharia-compliant covered-card description. The issuer’s foreign-currency service charge also needs its applicable VAT and separate scheme treatment made explicit; we do not claim a precise all-in rate or a fee advantage.
Is it worth it?
For a UAE household spending across groceries, fuel, school fees, dining and utilities, the ADIB Cashback Visa returns a strong 4% on exactly those lines — with no minimum-spend gate, a low AED 5,000 salary bar, and a modest AED 99 fee. As a Sharia-compliant pick it sits alongside DIB’s household card, edging it on rate (4% vs 3%) and on the absence of a spend gate.
The current product copy and the earlier structure description are not reconciled, so we use the general Sharia-compliant covered-card description. The issuer’s foreign-currency service charge also needs its applicable VAT and separate scheme treatment made explicit; we do not claim a precise all-in rate or a fee advantage.
Bottom line
A strong household-categories Islamic cashback card — 4%, no spend gate — that earns nothing beyond its five categories. Apply if your spend fits and you’ll pair it with a general card. Skip if you want rewards on everyday or international spend.
Live offers from Abu Dhabi Islamic Bank
Bank-wide offers; each deal lists the cards that qualify.
- Lulu online — 20% off up to AED 50 every Thursday with an ADIB Visa Covered Card, to 31 December Ends 31 Dec
- Careem Food — 30% off up to AED 50 with an ADIB Visa Covered Card, to 5 January 2027 Ends 5 Jan · Code ADIB30