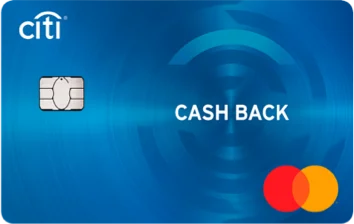
The Citi Cash Back is a cashback Mastercard without a minimum-spend gate. Eligible purchases, the assigned credit limit and transaction exclusions still determine what earns cashback, which is credited automatically to the card.
- Annual fee
- AED 315 incl. VAT
- Min salary
- AED 8,000/mo
No annual fee in year one. From year two, the fee above applies unless you meet Citi’s annual-spend waiver. Check the current Citi Cash Back terms on Citi’s website.
Pros
- Cashback on eligible purchases without a minimum-spend gate; assigned-credit-limit and transaction exclusions apply
- No annual fee in year one, waived from year two at a low AED 9,000 annual spend
- Cashback is credited automatically — nothing to track or redeem
- 8 airport lounge visits a year via Mastercard Travel Pass
- Small everyday extras — a Careem airport ride and monthly Talabat discount
Cons
- Foreign-currency cashback is not a precise net return; the full conversion and processing cost needs checking
- 1% base rate is modest for everyday local spend
- Lounge access only unlocks with non-AED spend
- AED 8,000 minimum income
- 44.28% APR — only worth holding if you clear the balance in full
Cashback
Cashback is uncapped (up to your credit limit) with no minimum spend:
- Everything else
- Pending
No spend above assigned credit limit earns cashback; utility bill payments via bank channels excluded. Stored rates may display only subject to these conditions; unrestricted total-return estimate is not source-qualified.
Fee summary
Our figures include VAT: Citi’s AED 300 base annual fee is AED 315 with 5% VAT, and it’s free in year one and waived from year two if you spend at least AED 9,000 in the year. The fixed retail/cash APR is 44.28% — relevant only if you carry a balance.
Welcome offer breakdown
Citi’s own product page advertises an AED 300 joining-bonus statement credit for eligible direct applicants after AED 6,000 of qualifying spend within 60 days. We verified the offer on that page, not through a partner. If you arrive from another link, check the offer and conditions shown for that application before counting on the credit.
See how the welcome offer differs from the annual fee waiver.
What you get — per-benefit value
Cashback on eligible domestic spend
Use the source-qualified earning rows for your actual transactions. The assigned credit limit and exclusions prevent an unrestricted, linearly scaled annual-return estimate. No minimum-spend gate does not mean that every purchase earns cashback.
3% on non-AED spend
The published international processing margin is not proof of an exact net overseas return. Check the full conversion and processing terms rather than subtracting one issuer percentage from the cashback headline.
8 lounge visits (Mastercard Travel Pass)
Unlocked by a non-AED purchase. At the AED 200 walk-in equivalent: Value to me: AED 800/year on four flown trips, AED 1,600/year at the full ration.
Careem ride and Talabat discount
One Careem airport ride a year (up to AED 84) and 20% off one Talabat order a month (up to AED 14) — AED 84 + AED 168 at full utilisation. Value to me: AED 0–252/year. Small numbers, honestly stated.
AED 300 welcome credit
Statement credit advertised on Citi’s product page after AED 6,000 of qualifying spend within 60 days. Value in this example: AED 300 once, if those terms apply and you meet them.
No combined annual package value is quoted while reward or benefit conditions remain unconfirmed. Check the current fee and waiver separately rather than assuming that advertised perks recover the cost.
Key conditions to know
- No minimum spend
- Cashback is earned from the first dirham, with no caps up to your credit limit — unusually simple for a UAE cashback card.
- Excluded spend
- No cashback on amounts above your credit limit in a cycle, or on utility-bill payments through Citi online, mobile or phone channels.
- Lounge access
- 8 visits a year to 1,200+ lounges via Mastercard Travel Pass, conditional on non-AED spend; further visits are charged.
- Everyday extras
- One complimentary Careem airport ride a year (up to AED 84) and 20% off Talabat (up to AED 14) once a month.
- Eligibility
- Minimum income AED 8,000/month; age 18 or older; UAE resident.
Watch out for
- The published international processing margin is not proof of an exact net overseas return. Check the full conversion and processing terms rather than subtracting one issuer percentage from the cashback headline.
- Different reward conditions. Compare eligible categories, credit-limit restrictions and exclusions rather than contrasting isolated headline percentages.
- Lounge gating. You need a non-AED purchase to unlock the lounge visits.
- Utility exclusion. Paying DEWA/etc. through Citi’s channels earns no cashback.
Is it worth it?
Consider it if automatic cashback on eligible purchases fits your needs and you can meet the fee-waiver conditions without extra spending. Confirm the assigned credit limit, exclusions, eligibility and benefit terms; this is not cashback without rules or a market-wide recommendation.
Calibrate expectations on overseas spending: the complete conversion cost needs checking before the cashback can be treated as a net return. Compare the eligible domestic reward with any category card you would actually use, including its caps and qualification conditions.
Bottom line
A no-minimum-spend cashback card subject to the assigned credit limit and exclusions. Consider it for straightforward eligible domestic purchases. Look elsewhere if you need a guaranteed overseas profit or a higher category headline without checking its caps and conditions.
Live offers from Citibank
Bank-wide offers; each deal lists the cards that qualify.
- dnata Travel — extra 5% off selected hotel packages with code CITIBANK, book by 15 December Ends 15 Dec · Code CITIBANK
- Styli — 20% off full price, 10% off sale with a Citi card, to 31 December Ends 31 Dec
- fnp.ae — 15% off flowers and gifts with a Citi card, to 31 March 2027 Ends 31 Mar · Code CITI15
- NRTC Fresh — 10% off online grocery orders of AED 80 or more with a Citi card, to 31 March 2027 Ends 31 Mar