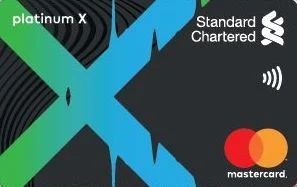
The Standard Chartered Platinum X is a high-rate but highly conditional cashback Mastercard: up to 10% back, but only on specific spend channels and tiered by how much you spend each month.
- Annual fee
- AED 525 incl. VAT
- Min salary
- AED 5,000/mo
Pros
- Up to 10% cashback on qualifying online, foreign-currency and mobile-wallet spend, subject to tiers and caps
- Unlimited complimentary access to 20+ local and international airport lounges via Mastercard
- Low AED 5,000 minimum income; first year fee-free
- Cleartrip and Expedia travel discounts
Cons
- Cashback only on online, foreign-currency and mobile-wallet channels — regular in-store swipes earn nothing
- The 10% rate needs AED 15,000+ total monthly spend; most users earn 3-5%
- Foreign-currency returns need the full issuer and scheme-processing cost checked
- Per-channel caps (AED 400 / 400 / 200) limit total cashback to about AED 1,000/month
- Carrying a balance can outweigh the cashback; confirm finance charges before applying
Cashback
The issuer uses monthly-spend tiers and separate channel caps. A top-tier headline is not a universal comparison rate; the source-qualified tier schedule and unresolved model conditions control any return estimate.
- Everything else
- Pending
Source uses four monthly-spend tiers and separate channel caps. Current stored headline rate at the lowest qualifying spend materially overstates rewards.
Fee summary
The card is free in year one, then AED 525 (any ongoing waiver requires current product-specific confirmation). The foreign-currency fee is up to 2.99%, and the cash-advance fee is 3.15% (min AED 105). The retail monthly finance charge is recorded from the current product-specific fee block. The captured shared price guide did not establish this product’s annual rate, so that figure is withheld rather than calculated from the monthly charge. As with any cashback card, clear the balance in full.
What you get — per-benefit value
Channel cashback (online / foreign-currency / mobile wallet)
Worked at the middle tier: AED 8,000 of total monthly spend (5% rate), of which AED 4,000 online (AED 200, within the applicable channel cap) and AED 2,000 by mobile wallet (AED 100, inside the AED 200 cap): AED 300/month. Value to me: ~AED 3,600/year on that profile. At the top tier — AED 15,000+ of monthly spend with all three channel caps maxed — the ceiling is ~AED 1,000/month, ~AED 12,000/year. An in-store swiper earns AED 0 regardless of spend.
Foreign-currency cashback
Foreign-currency cashback depends on the spend tier and channel cap. The issuer publishes an FX upper bound and says scheme processing is additional. That does not establish an exact all-in fee, so no precise net overseas profit or break-even claim is included in this review.
Unlimited lounge access (20+ lounges)
A smaller network than the 1,000+ Visa Airport Companion lists, but uncapped. At the AED 200 walk-in equivalent: Value to me: AED 800/year on four trips that route through covered lounges; scales with your actual travel.
Total package: ~AED 3,600 of channel cashback at the worked middle tier plus ~AED 800 of lounge value is roughly AED 4,400/year against the AED 525 standard annual fee (the current product confirms the first-year waiver; an ongoing spend waiver is not established). The maths holds only if your spend genuinely lives online and in the mobile wallet — for a physical-card spender the package is the lounge access and nothing else.
Key conditions to know
- Qualifying channels
- AED online, non-AED foreign currency, and AED mobile-wallet spend only. In-store physical-card swipes and contactless taps (not via a mobile wallet) earn no cashback.
- Spend tiers
- Cashback rate is set by total monthly spend across the card: 0% below AED 2,500, then 3% / 5% / 10% at AED 2,500 / 7,500 / 15,000.
- Caps
- AED 400/month online, AED 400/month foreign currency, AED 200/month mobile wallet — about AED 1,000 total.
- Lounge access
- Unlimited complimentary access to 20+ local and international lounges via Mastercard — a smaller network than the 1,000+ Visa Airport Companion lists, but uncapped.
- Eligibility
- Minimum income AED 5,000; age 21-60; UAE resident.
Watch out for
- The swipe trap. If you mostly tap or insert the physical card in shops, this card earns nothing — its cashback lives entirely online, abroad, and in the mobile wallet.
- The 10% mirage. 10% only kicks in above AED 15,000 of monthly spend; below that lower tiers apply. Foreign-currency cashback is not an exact net profit after all fees.
- Caps. ~AED 1,000/month total ceiling across the three channels.
- Finance charges. The fee block uses the current product-specific retail monthly charge; no unsupported annual figure is inferred from it.
Is it worth it?
For a heavy spender whose purchases run through online checkouts, foreign-currency transactions and mobile-wallet taps — and who clears AED 7,500-15,000+ a month — the Platinum X offers channel-specific cashback, subject to the applicable tiers and caps. Check its lounge conditions and published eligibility separately; this is not a market-wide return ranking.
For everyone else it underwhelms: a typical in-store swiper earns nothing, the 10% needs heavy spend, and the full cost of foreign-currency spending needs checking. It’s a specialist card, not a default one.
Bottom line
A high-ceiling, high-condition cashback card for online/mobile-wallet-heavy big spenders. Apply if your spend fits the three channels and you’ll hit the higher tiers. Skip if you mostly swipe a physical card in-store — it earns you nothing.
Live offers from Standard Chartered
Bank-wide offers; each deal lists the cards that qualify.
All live deals →