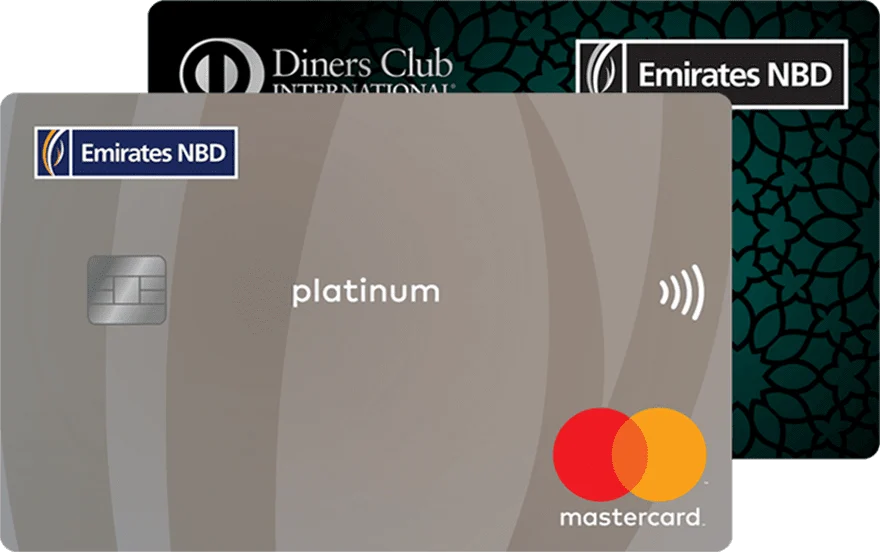
The Emirates NBD Duo is the bank’s dual-card product — a Diners Club and a Mastercard issued on a single credit limit, with the earn assessed across the two cards together as Plus Points. The pitch is network redundancy plus a category-bonus earn on grocery, fuel and utility spend; the fine print is a spend gate, a points cap, and Abu Dhabi residency.
- Annual fee
- Free year 2+
- Min salary
- AED 12,000/mo
Pros
- AED 0 annual fee on the current promo (vs SoC standard AED 840 if the waiver lapses)
- Dual-network rails — a Diners Club and a Mastercard on one credit limit, useful for network redundancy and at Diners-accepting merchants
- Plus Points can be redeemed through the issuer’s specified channels, subject to their current conversion terms.
- The issuer publishes product-specific rewards and benefits that can be checked against your actual use.
Cons
- Plus Points accrual is not a cash percentage. Read the exact native-unit rows, reduced categories and statement cap alongside the redemption channel; statement cashback is below the selected non-cash redemption value.
- Plus Points cap of 500 per statement limits effective return at higher spend
- The published foreign-currency percentage is the VAT-inclusive issuer fee, not an all-in conversion cost; scheme processing and any acquirer charges may be additional.
- Merchant exclusions, reward caps and benefit conditions can change the headline value.
- Application-specific salary-transfer conditions remain unconfirmed in the reviewed public terms.
Earn rates
The boosted Plus Points rows apply to defined categories and qualifying monthly spending. Native points are not themselves a cash percentage:
- Grocery, electronics, utilities, education and fuelOnly listed categories; minimum monthly spend AED 5,000 per statement; otherwise 1.5%; max 500 Plus Points per statement.
- 5% as ENBD Plus PointsSource-stated qualifying rate
- Qualifying other spendOther qualifying spend including travel, dining, hotels and online; max 500 Plus Points per statement.
- 0.5% as ENBD Plus PointsSource-stated qualifying rate
Native Plus Points and source-stated percentage rows are not unconditional cash returns. Cashback redemption is AED 0.75 per point, while selected non-cash redemptions are AED 1. Per-statement caps and exclusions apply.
Fee summary
Read the joining fee, renewal fee and any promotional waiver separately. A renewal figure is not the complete first-year cost, and a current application promotion is not a guarantee that every applicant receives it. The fee table carries the source-qualified VAT treatment. The foreign-currency fee shown is the issuer’s charge, not a total conversion-cost quote. The issuer fee guide states that scheme processing and any acquirer charges may be additional. A merchant’s AED-conversion offer can add a different cost; an issuer-fee waiver does not remove every possible overseas charge.
What you get — per-benefit value
The Duo earns ENBD Plus Points. Their cash value depends on the redemption route; statement cashback and selected non-cash redemptions have different published values. Read the native-unit earning rows and redemption conditions together rather than treating the headline as an unconditional cash return.
Plus Points on qualifying categories
Use the named category rows, qualifying-spend threshold and combined statement cap in the source-qualified earning table. Purchases outside those conditions do not automatically receive the boosted rate.
Buy-1-get-1 movie ticket at Royal Cinemas
A named benefit is not evidence of unlimited visits, guest admission or an unrestricted booking allowance. Use the current issuer/provider conditions for the qualifying spend, booking channel, fees and usage limit; unconfirmed allowances are not used for benefit matching.
Airport lounge access
Lounge access is described by the issuer, but the applicable provider, visit allowance and qualification conditions need confirming for the exact card. No cash value is assigned to an unconfirmed allowance.
Golf access
Complimentary access to top UAE courses per the issuer free-text — no round cap or course list published, so we put no AED figure on it. Worth something to a golfer, AED 0 to everyone else.
A named benefit is not evidence of unlimited visits, guest admission or an unrestricted booking allowance. Use the current issuer/provider conditions for the qualifying spend, booking channel, fees and usage limit; unconfirmed allowances are not used for benefit matching.
Key conditions to know
- Two cards, one account
- The product issues two physical cards — a Diners Club and a Mastercard — on a single credit limit and a single statement. Spending on either card draws on the same limit, and the Plus Points cap is assessed across the combined statement.
- Boosted earning — conditions
- Use the named categories and qualifying monthly-spend condition in the earning table. The points earned and their cash redemption value are different measures.
- Plus Points cap
- Read the combined statement cap in the source-qualified earning rows. The two cards do not create two independent reward caps.
- Abu Dhabi residency clause
- The Schedule of Charges note on this product reads “exclusive for Abu Dhabi residents only”. Confirm with your ENBD branch whether this clause currently applies to your application.
- Foreign-currency fee
- The published foreign-currency percentage is the VAT-inclusive issuer fee, not an all-in conversion cost; scheme processing and any acquirer charges may be additional.
- Eligibility
- The issuer product page states a minimum monthly salary of AED 12,000. The reviewed product, Key Facts Statement and shared credit-card terms do not establish a universal salary-transfer requirement. Confirm the conditions of your own application; we do not assume a transfer-related clawback or that none can apply.
Watch out for
The foreign-currency fee shown is the issuer’s charge, not a total conversion-cost quote. The issuer fee guide states that scheme processing and any acquirer charges may be additional. A merchant’s AED-conversion offer can add a different cost; an issuer-fee waiver does not remove every possible overseas charge.
Bottom line
An Abu Dhabi-resident card package whose boosted categories depend on qualifying monthly spend and a shared statement cap. It makes sense only if your real purchases fit those conditions and the benefits you can actually use justify the cost. Confirm pending qualification and benefit terms before applying.
Source status and open questions
The source-notes panel identifies pending fields and any conflicting issuer terms. The original whole-card verification and scrape dates have not been advanced by this scoped review. Pending does not mean zero, free or guaranteed.
Sources: issuer product page; shared credit-card terms, and the relevant programme documents linked by the issuer.
Live offers from Emirates NBD
Bank-wide offers; each deal lists the cards that qualify.
- Yas Island theme parks — 30% off one-day tickets online with an Emirates NBD card, to 21 December
- Right Bite — 20% off 20, 40 and 60-day meal plans with an Emirates NBD card, to 31 December · Code ENBD20
- Urban Company on noon — 5% back in credits with the Emirates NBD noon One card, through 31 December · Code ENBD
- Zuvees — 15% off flower arrangements with an Emirates NBD Infinite, Signature or World Elite card, to 31 December · Code ENBD15