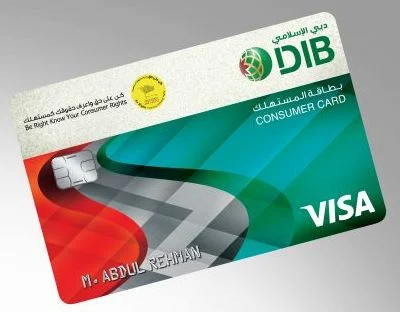
The DIB Consumer Cashback Reward Card is a Sharia-compliant Visa that pays 3% cashback on a fixed set of UAE household categories — and nothing outside them.
- Annual fee
- AED 210 incl. VAT
- Min salary
- AED 5,000/mo
Pros
- 3% cashback across a broad set of UAE essentials — groceries, fuel, school fees, utilities, telecom, Salik/Nol and car servicing
- Sharia-compliant, with takaful travel and medical cover up to US$100,000 and roadside assistance
- Low AED 5,000 minimum salary
- First year free under a limited-time offer
Cons
- Nothing outside the listed categories earns cashback — a bills-and-essentials card, not a general earner
- Tight caps (AED 100 on fuel, utilities and telecom; AED 25 on Salik/Nol) under a AED 1,000 total monthly ceiling
- Requires AED 3,000 of retail spend each statement cycle to earn anything (since 10 May 2025)
- AED 210 annual fee after the first year; no general welcome bonus
- Utility and government bills paid via DIB's own channels earn no cashback
Earn rates
Cashback is 3% on the listed categories only, each with its own monthly cap. The table below shows the categories our comparison engine can map; the full list is in the note:
- Everything else
- Pending
Fee summary
The current specific cards schedule states a monthly Salam upper bound that differs from the older Wajaha document used previously. The finance-rate field remains pending; do not treat the previously recorded percentage as a current exact rate. The fee block above distinguishes confirmed costs from unresolved terms.
What you get — per-benefit value
3% cashback on the household-bills bundle
Illustration only, assuming eligible UAE purchases outside excluded bank bill-payment channels and the qualifying gate is met in every statement cycle: AED 2,500 supermarkets (AED 75), AED 500 fuel (AED 15, inside the AED 100 cap) and AED 800 of utilities and telecom (AED 24) a month is AED 114/month. That is AED 1,368 gross over twelve identical cycles, before card fees. This worked example is not an unrestricted annual-return estimate. School fees have a separate cap and are excluded from this scenario. The generic calculator is held until every relevant bill category and channel restriction is represented.
Takaful travel cover and roadside assistance
Travel and medical cover to USD 100,000 when flights go on the card, and twice-a-year roadside assistance. Value to me: AED 0 most years — both pay only when called on, and we don’t price insurance as an annual figure.
Compare the separately confirmed fee and any applicable waiver against rewards you could actually earn. This review does not promise an annual package value or a fee-recovery period. Listed categories, caps, eligibility and payment-channel exclusions still apply.
Key conditions to know
- Minimum spend
- Since 10 May 2025, AED 3,000 of retail purchases per statement cycle is required before any cashback is earned.
- Caps
- Per-category monthly caps (AED 300 / 200 / 100 / 25 depending on category; groceries and school fees AED 200 since 10 October 2026) under a AED 1,000 total monthly ceiling. Cashback is on UAE transactions only.
- Excluded spend
- Anything outside the listed categories earns nothing, as do utility and government bills paid through DIB’s own platforms.
- Travel cover
- Travel and medical cover up to US$100,000 via Watania takaful for the cardholder, spouse and up to four children under 18, when flights are booked on the card.
- Eligibility
- Minimum monthly salary AED 5,000; UAE residency required.
Watch out for
- No general earn. This is the defining limit: dining, general retail and international spend earn 0%. Pair it with a flat-rate card for everything else.
- The AED 3,000 gate. Spend under AED 3,000 in a cycle and you earn nothing that cycle, even on bills.
- Small caps on small categories. Salik/Nol caps at AED 25 and fuel/utilities/telecom at AED 100 — useful but quickly maxed.
- High FX fee. 3.70% on foreign-currency spend; not a card for travel purchases.
Is it worth it?
For a UAE household with school fees, a weekly supermarket shop, fuel and the usual utility and telecom bills, the DIB Consumer Cashback Card returns a genuine 3% across exactly those line items — and as a Sharia-compliant card with family takaful cover and a low AED 5,000 salary bar, it slots neatly alongside a current account.
As a standalone or general-spend card it falls short: zero on dining, retail and international, a AED 3,000 monthly gate, and a AED 1,000 cap. Treat it as a dedicated bills card, not your everyday earner.
Bottom line
A focused, Sharia-compliant household-bills cashback card. Apply if your spend concentrates in its categories and you’ll clear AED 3,000 a month. Skip if you want rewards on general, dining or international spend.
Live offers from Dubai Islamic Bank
Bank-wide offers; each deal lists the cards that qualify.
- Air Arabia — 20% off Ultimate and 10% off Value fares with a DIB Visa Covered Card, book by 15 November Ends in 4 days · Code DIB
- Mann Marzi Restaurant — 15% off the bill with a DIB Covered Card or Johara Debit Card, to 30 November Ends 30 Nov
- Choix, InterContinental Dubai Festival City — 20% off à la carte, afternoon tea and cakes with a DIB Covered Card, to 31 December Ends 31 Dec
- Dr. Nutrition app — up to 20% off by product line with a DIB Covered Card, to 31 August 2027 Ends 31 Aug · Code DIB15